Construction Appraisals for Rural Land in Oklahoma
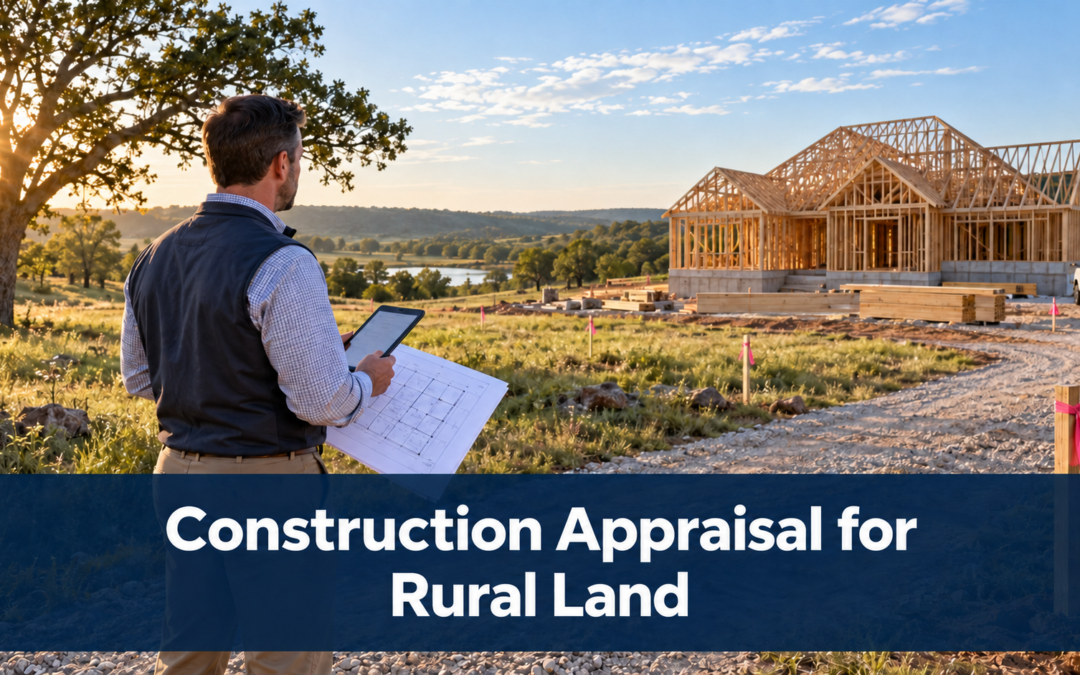
Building a home on rural land can be an exciting opportunity, but before construction financing can be finalized, the lender must determine what the completed property is expected to be worth. This is where a construction appraisal becomes essential.
A construction appraisal helps establish the home’s estimated future value and determines how much financing may be available for the project.
What Is a “Subject to Completion” Appraisal?
Because the home has not yet been built, the appraiser cannot inspect a finished property. Instead, the appraisal is completed “subject to completion.”
The appraiser estimates the future value of the completed home using:
- Architectural plans and floor plans
- Building specifications
- Construction materials and finishes
- The proposed construction budget
- The value and characteristics of the land
- Sales of comparable homes in the surrounding market
The final value is based on the assumption that the home will be completed according to the plans and specifications provided.
What Appraisers Consider on Rural Oklahoma Properties
Rural properties often have characteristics that are not commonly found in suburban neighborhoods. These details can affect the property’s usability, marketability, and estimated value.
A rural construction appraisal may focus heavily on:
- Road access and recorded easements
- Rural water availability or private well systems
- Septic systems
- Electric and other utility availability
- Acreage size
- Topography and overall land usability
- Floodplain considerations
- Local housing demand
- Distance from employment centers, schools, shopping, and services
- Comparable rural-home sales in the surrounding area
Why Comparable Home Sales Matter
Comparable sales are recently sold properties that are reasonably similar to the proposed home in location, size, design, acreage, quality, and features.
The more similar rural-home sales available in the area, the more reliable the appraisal will generally be. Appraisals may become more challenging when the proposed home is highly customized or includes features that are uncommon in the local market.
Examples may include:
- Barndominiums
- Very large homes on acreage
- Accessory dwelling units
- Oversized detached garages or workshops
- Swimming pools
- Unusual construction materials or designs
- Properties located far from other residential development
These features do not automatically make a project ineligible. However, the appraiser must find enough market evidence to support their value.
How the Appraisal Can Affect Your Construction Loan
A construction appraisal helps determine the maximum loan amount a lender can approve. If the appraised value supports the project’s total cost, financing may proceed as planned.
If the appraisal is lower than expected, the borrower may need to:
- Modify the home’s design or specifications
- Reduce certain construction costs
- Contribute additional funds
- Use available land equity
- Reconsider features that are not well supported by the local market
The construction cost does not always equal the completed home’s market value. A feature may be expensive to build without adding the same amount to the property’s appraised value.
How to Prepare for a Stronger Appraisal
Careful planning before the appraisal is ordered can help reduce surprises.
Borrowers should work with their lender and builder to provide:
- Complete architectural plans
- Detailed construction specifications
- A realistic and itemized construction budget
- A clear description of materials and finishes
- Information about wells, septic systems, utilities, and site improvements
- Documentation for any recently completed land improvements
- A home design that fits the surrounding rural market
It is also important to select an experienced builder who understands local construction costs, permitting requirements, and rural-site preparation.
Why Construction Appraisals Protect Borrowers
Although an appraisal adds to the upfront cost of a construction project and may sometimes limit borrowing power, it provides an important layer of protection.
The appraisal helps confirm that the proposed home and construction budget are reasonably supported by the local real estate market. This can help borrowers avoid becoming financially overextended on a project that may not be worth its total construction cost when completed.
Plan Your Rural Construction Loan With an Experienced Team
A successful rural construction project begins with realistic plans, an accurate budget, a qualified builder, and a home design that fits the local market.
Spurr Mortgage has 35 years of experience helping Oklahoma borrowers navigate land and one-time-close construction financing. Our team can help you understand the appraisal process, evaluate your construction plans, and determine whether your land equity may be used toward your new home.
Contact Spurr Mortgage at 405-348-9919 to discuss your rural property and construction financing options.
All loans are subject to credit approval, property eligibility, appraisal requirements, and applicable lending guidelines.